2026-11-17
Home
Japanese
Omega Investment Co., Ltd.
FURYU (First read : 6238)
A ¥3 billion buyback changes the equation; 15% ROE could reset the valuation
| Share price ¥1,505 (Nov. 13 close) | Forecast EPS ¥94.39 | Actual BPS ¥895.01 (Sep. 30) | Forecast dividend ¥40.00 |
| Simplified ROE 10.5% | Forecast P/E 15.9x | P/B 1.68x |
| Click here for the PDF version of this page |
| PDF version |
First Read | The buyback matters. Now margins must follow
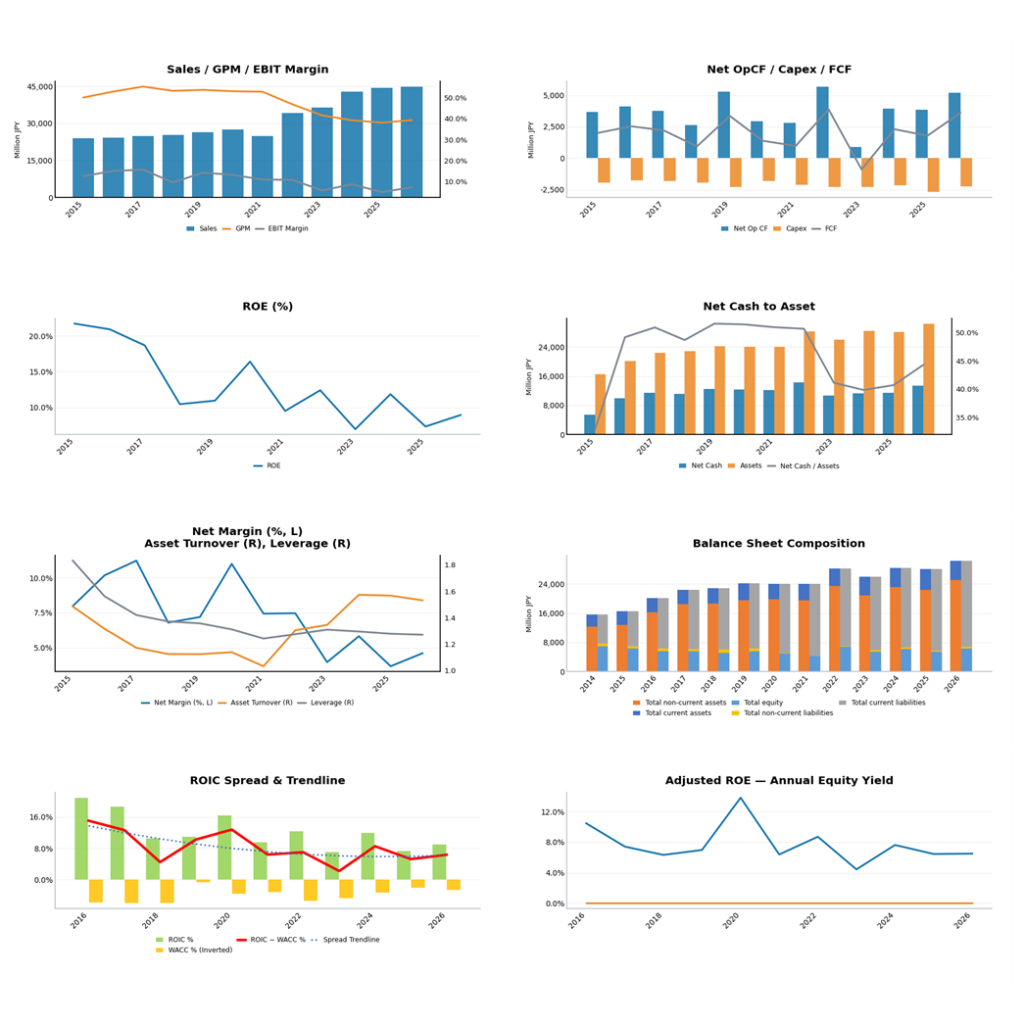
The most important announcement is the decision to repurchase up to ¥3 billion of shares, with a ceiling of 9.43% of shares outstanding excluding treasury stock. This is tangible action on a longstanding issue: putting FURYU’s substantial capital base to work for shareholders. The FY March 2028 target of ROE of 15% or higher now looks more achievable, supported by first-half earnings growth and a more active capital policy. It remains demanding: operating profit must rise 50%, from this year’s ¥4.0 billion target to ¥6.0 billion. Yet investors should not overlook the other side of that challenge. If management repeatedly delivers earnings and capital-efficiency improvements that exceed the market’s cautious expectations, the stock could benefit not only from EPS growth but also from a pronounced expansion in its valuation multiple.
Earnings Drivers | Sales surprise; margin conversion still to prove
First-half revenue rose 17.7% to ¥25.28 billion, while operating profit gained 13.2% to ¥2.03 billion. FURYU raised full-year revenue guidance from ¥48.0 billion to ¥54.0 billion but kept its ¥4.0 billion operating-profit forecast. Arcade prizes and overseas merchandise are driving SEKAIKAN business revenue. However, yen weakness and product mix are weighing on margins. Management estimates an ¥800 million annual operating-profit headwind from foreign exchange. GIRLS Trend remains highly profitable in its established business, while declining PiCTLINK subscriptions and spending on new activities warrant attention.
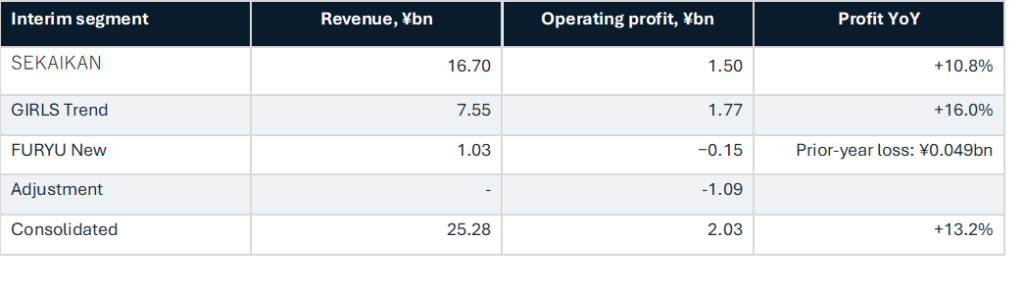
Second-quarter operating profit alone fell 12.3% year over year to ¥959 million. October sales, however, rose 26.9% to ¥4.31 billion. Demand remains firm; the question is whether stronger orders will translate into better second-half margins.
Equity Implications | Can execution overturn cautious expectations?
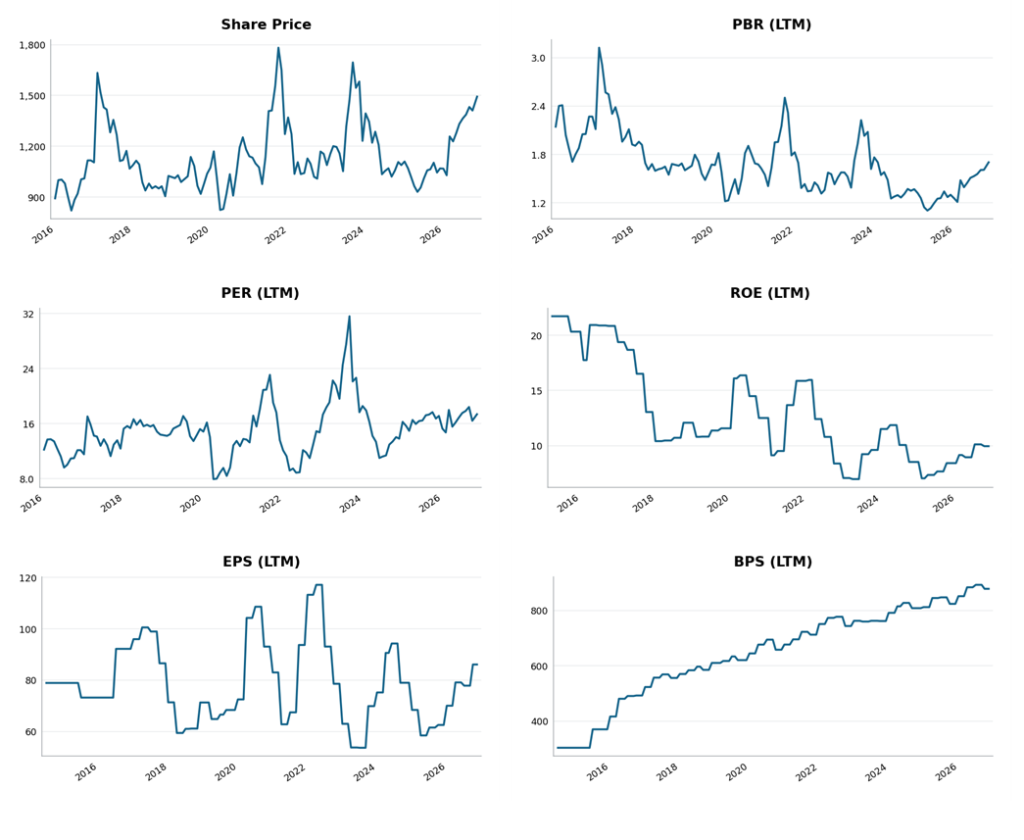
We retain a positive medium- to long-term view. At the November 13 closing price of ¥1,505, forecast P/E is 15.9x, P/B is 1.68x, and simplified forecast ROE is 10.5%. The repurchase is authorized, not yet completed. Reaching 15% ROE will require improved Worldview margins, resilient Girls Trend earnings, and smaller losses in newer businesses. Over the next one to two years, margin delivery and repurchase execution are key; over three to four years, the results of international IP expansion and capital allocation will be key. It would be premature to price in full delivery, but sustained results that outpace market expectations could support a material rerating alongside earnings growth. We will revisit the formal investment view and fair value in an upcoming Update Report after further review of the results and management commentary.
Company Profile | FURYU develops photo-booth machines and PiCTLINK, licensed character goods and crane-game prizes, premium collectibles, video games, and anime across SEKAIKAN, Girls Trend, and FURYU New businesses.
Note: BPS is our calculation of September 2026 equity of ¥23,716,575 thousand divided by 26,498,070 shares excluding treasury stock. Forecast ROE is FY EPS guidance divided by latest actual BPS. The ¥1,505 closing share price preceded the earnings release; after-hours reactions are not reflected.
References: FY March 2027 interim release and presentation; FY guidance revision; share repurchase decision; U.S. subsidiary capital increase; October monthly update; October 2026 Basic Report; share-price history; FactSet 6 Charts and 8 Charts.
FURYU (6238) | Share Price and Valuation History
FURYU (6238) | Financial Performance and Capital Efficiency