2026-11-17
Home
Japanese
Omega Investment Co., Ltd.
LIFULL (First read : 2120)
HOME’S earnings power moves into focus; underlying FY2027 operating profit could reach ¥5bn
| Share price ¥252 (Nov. 12 close) | Forecast EPS ¥22.20 | Actual BPS ¥217.99 (Sep. 30) | Forecast dividend ¥8.17 |
| Simplified ROE 10.2% | Forecast P/E 11.4x | P/B 1.16x |
| Click here for the PDF version of this page |
| PDF version |
First Read
The key takeaway from the earnings results is not the modest 3.6% increase in consolidated operating profit. HOME’S Services delivered simultaneous growth in customer count and revenue per customer. LIFULL’s FY2027 operating profit guidance of ¥4.2 billion includes ¥0.8 billion of one-time office relocation and security costs. Excluding these items, management points to ¥5.0 billion of operating profit, a meaningful reference point against its FY2028 target of ¥5.5–6.0 billion. This adjusted figure is management’s scenario, not a guaranteed recurring earnings level.
The Earnings Core | HOME’S funds the investment agenda
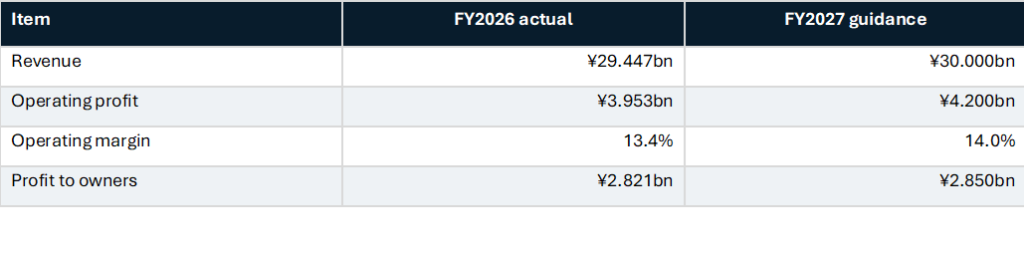
FY2026 revenue grew 4.7% to ¥29.447 billion, while operating profit rose 3.6% to ¥3.953 billion. On a twelve-month average basis, HOME’S Services reached 34,228 customers and ¥65,205 in average revenue per agent, both higher year over year. Although increased growth investment led to a decline in the segment margin from 16.9% to 16.3%, segment profit reached a record ¥4.36 billion. The 46.9% decline in profit attributable to owners chiefly reflects the unusually large nonrecurring benefit from the prior-year restructuring of discontinued overseas operations. The operating trend deserves greater weight.
Implications for Equity Value | A credible, demanding margin target
FY2027 guidance calls for ¥30.0 billion in revenue, ¥4.2 billion in operating profit and EPS of ¥22.20. The implied operating margin is 14.0%. Excluding ¥0.8 billion in one-time costs, underlying operating profit would reach ¥5.0 billion, implying a margin of 16.7%, above management’s FY2028 target of over 15%. Going forward, we will assess whether these one-time costs fall away and whether the underlying profitability is sustainable. A larger customer base and AI-driven sales and development productivity could challenge investors’ conservative expectations. But guided FY2027 revenue growth of just 1.9% makes tangible AI-related profit contributions essential.
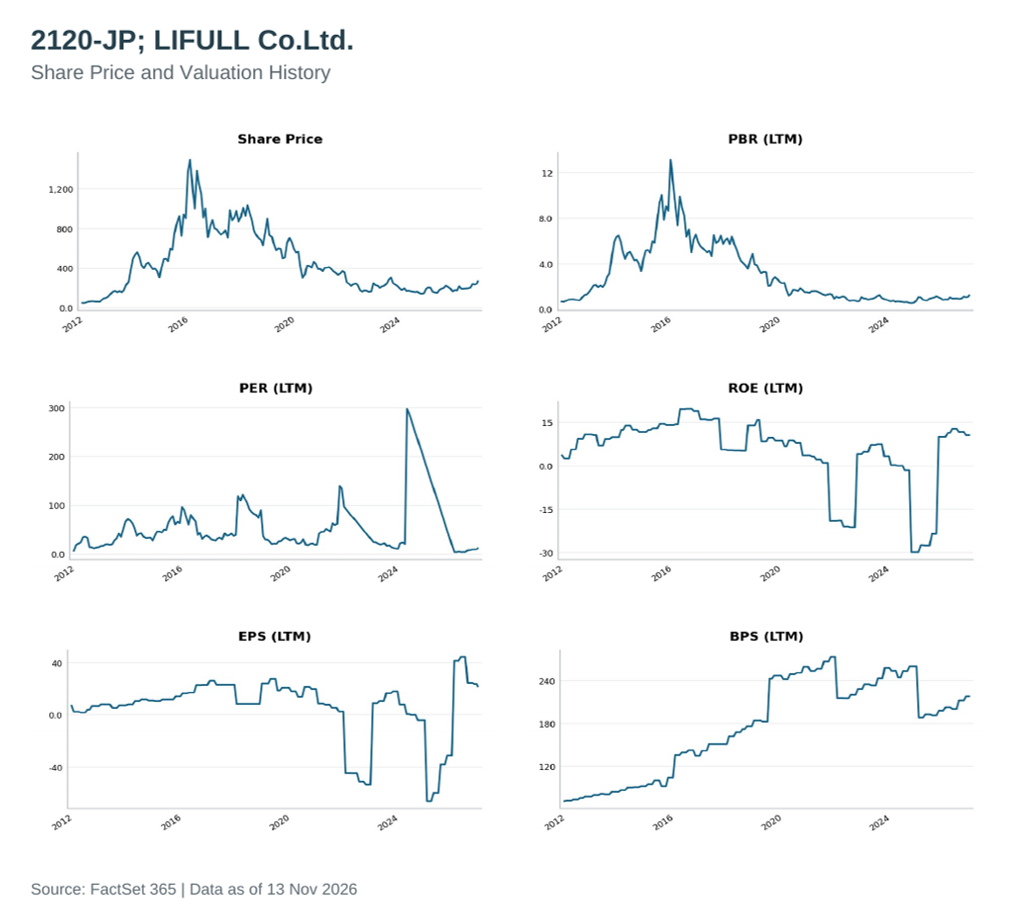
At the November 12 close of ¥252, forward P/E is 11.4x and P/B is 1.16x. The simplified forward ROE is 10.2%, and the indicated dividend yield is 3.2%. The company maintains a dividend payout ratio policy of 30% and has introduced a shareholder benefit program. Eligible shareholders receive annual benefits worth ¥30,000, bringing the combined dividend and benefit yield to approximately 6.2%*. Historical earnings volatility from the overseas restructuring still weighs on the valuation, but sustained profit growth in the core business could support both EPS appreciation and a meaningful re-rating. LIFULL deserves constructive consideration as a medium-term investment candidate. This is an initial investment assessment; we intend to conduct a more detailed analysis and present a formal investment view.
*The combined yield is calculated based on a share price of ¥252, ownership of 4,000 shares, and annual shareholder benefits worth ¥30,000. Eligibility generally requires continuous ownership for at least one year.
Company profile | LIFULL operates LIFULL HOME’S, a Japanese housing and property information platform, and related services for real estate businesses and home seekers. It is listed on the TSE Prime Market. President and CEO: Yuji Ito.
Metrics: ¥252 close on Nov. 12, 2026; company FY2027 forecast EPS ¥22.20 and dividend ¥8.17; reported Sep. 2026 BPS ¥217.99. Simplified ROE 10.2% = EPS/BPS; forward P/E 11.4x = price/EPS; P/B 1.16x = price/BPS. Calculated values are rounded to the displayed precision.
References: LIFULL FY2026 earnings release and earnings presentation (Nov. 12, 2026); Nov. 12 closing price.
LIFULL (2120) | Share Price and Valuation History
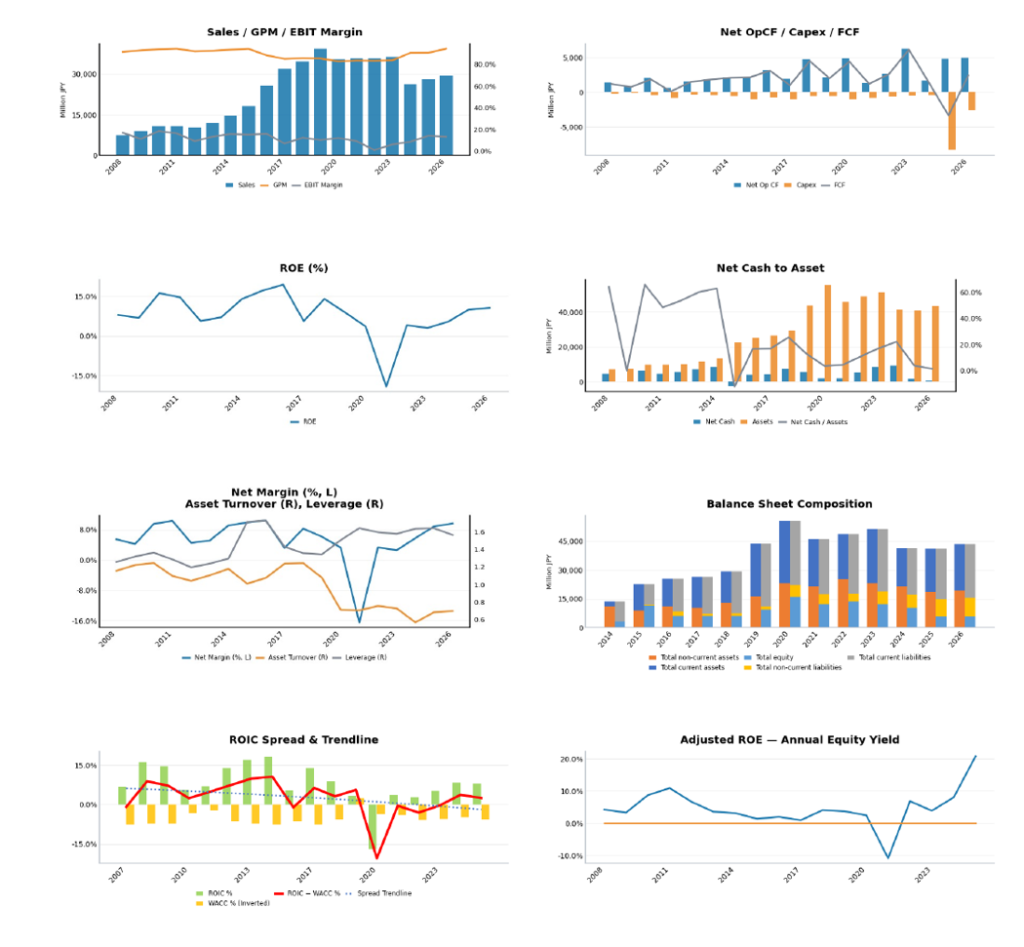
LIFULL (2120) | Long-term Trends in Performance, Financial Position, and Capital Efficiency