2026-11-16
Home
Japanese
Omega Investment Co., Ltd.
KOSAIDO Holdings (7868: Price Discovery)
Cautious BUY
| Share Price | Forecast EPS | Forecast PER | Actual BPS |
| 462 yen | 31.2 yen | 14.81 x | 333.61 yen |
| Actual PBR | Forecast ROE | Forecast Dividend | Dividend Yield |
| 1.38 x | 9.35 % | 13.34 yen | 2.89 % |
Conclusion
CAUTIOUS BUY : High barriers to entry, but limited confidence in earnings growth and capital efficiency
We assign a CAUTIOUS BUY rating. The cremation business, with its high share of the market in Tokyo’s 23 wards, is a strong earnings base whose locations and facilities are difficult to replicate and which stands to benefit from long-term demand growth. The expansion of funeral-related services also offers scope for earnings growth, and the shares offer investment appeal at JPY462, with a forecast PER of 14.81x and a PBR of 1.38x. However, these valuations alone do not establish that the shares are clearly undervalued. A forecast ROE of 9.35% cannot be said to demonstrate high capital efficiency. At the same time, uncertainties remain around social and administrative constraints on cremation fees, maintaining margins in funeral-related revenue-generating activities, project-driven fluctuations in funding requirements, and capital allocation discipline. While we rate the shares a buy in recognition of their competitive advantages, translating those advantages into sustained growth in earnings and FCF and into shareholder returns still requires verification. We therefore place our confidence one notch below that of a conventional BUY.
Profile
A funeral and information services group centred on cremation infrastructure in Tokyo’s 23 wards
KOSAIDO Holdings operates funeral public-interest and revenue-generating activities, information services, human resources and asset consulting, centred on six crematoria in Tokyo operated by its wholly owned subsidiary Tokyo Hakuzen. Its share of cremations in Tokyo’s 23 wards is reported to be 70% (as of March 2026, according to company-related materials), with legal restrictions on new crematoria and difficulties securing land and residents’ consent constituting barriers to entry. In FY3/2026, the shares of external revenue and segment operating margins were: Funeral Public-Interest Activities 15.0% (21.9%); Funeral Revenue-Generating Activities 29.0% (34.6%); Information 41.3% (4.4%); Human Resources 13.9% (-1.4%); and Asset Consulting 0.8% (-19.4%). The margins are calculated using revenue including intersegment transactions as the denominator.
Stock Hunter’s View
Providing cremation services of high public importance. Towards a society with rising deaths but no waiting times for cremation.
KOSAIDO HD operates four segments: Funeral, Information (Publishing and Web), Human Resources and Asset Consulting. Within Funeral, its subsidiary Tokyo Hakuzen operates six crematoria in Tokyo, accounting for a 70% share in the 23 wards (as of March 2026).
In principle, crematorium operations are governed by the Act on Cemeteries and Burial, etc., under which operators are, as a rule, local public bodies or, where that is more difficult, public-interest corporations or religious corporations. Tokyo Hakuzen, however, has operated crematoria in Tokyo since before the Act took effect (from the Edo to Meiji periods). In addition to the hurdles facing new entrants, establishing new crematoria is difficult because of costs and residents’ sentiments, making barriers to entry extremely high.
While many crematoria use trolley-type cremation furnaces, the company has adopted grate-type furnaces, which can complete cremations in less time, to accommodate rising cremation numbers. Consequently, it operates at seven to nine cycles per day, compared with the usual two to three cycles at other crematoria. Funeral Public-Interest Activities are affected by the number of deaths in Tokyo.
In addition, the company launched asset consulting services in 2023, mainly for users of its funeral halls, providing financial services such as handling inheritance procedures, inheritance tax filings by tax accountants and real-estate transactions.
For FY3/2027, the company plans revenue of JPY39.4bn (up 8.8% year on year) and operating profit of JPY7.1bn (up 5.3%). The first quarter began with declines in both revenue and profit, which the company attributes mainly to a business transfer and the reversal of large projects in the preceding year.
Investor’s View
Scarce cremation infrastructure is attractive, but challenges remain for sustained earnings growth and shareholder value enhancement
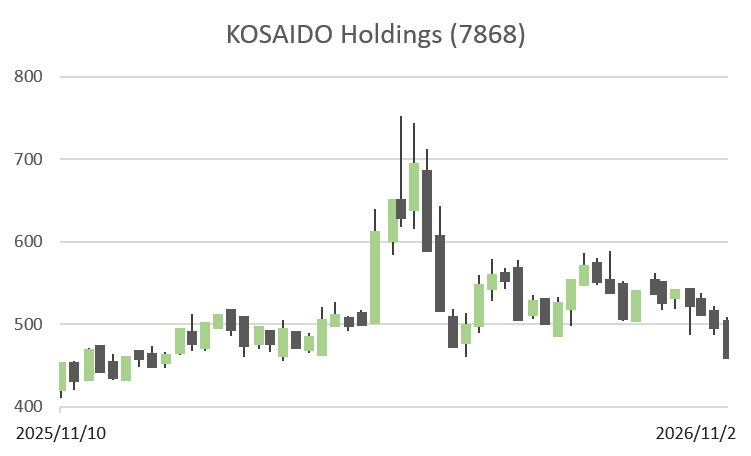
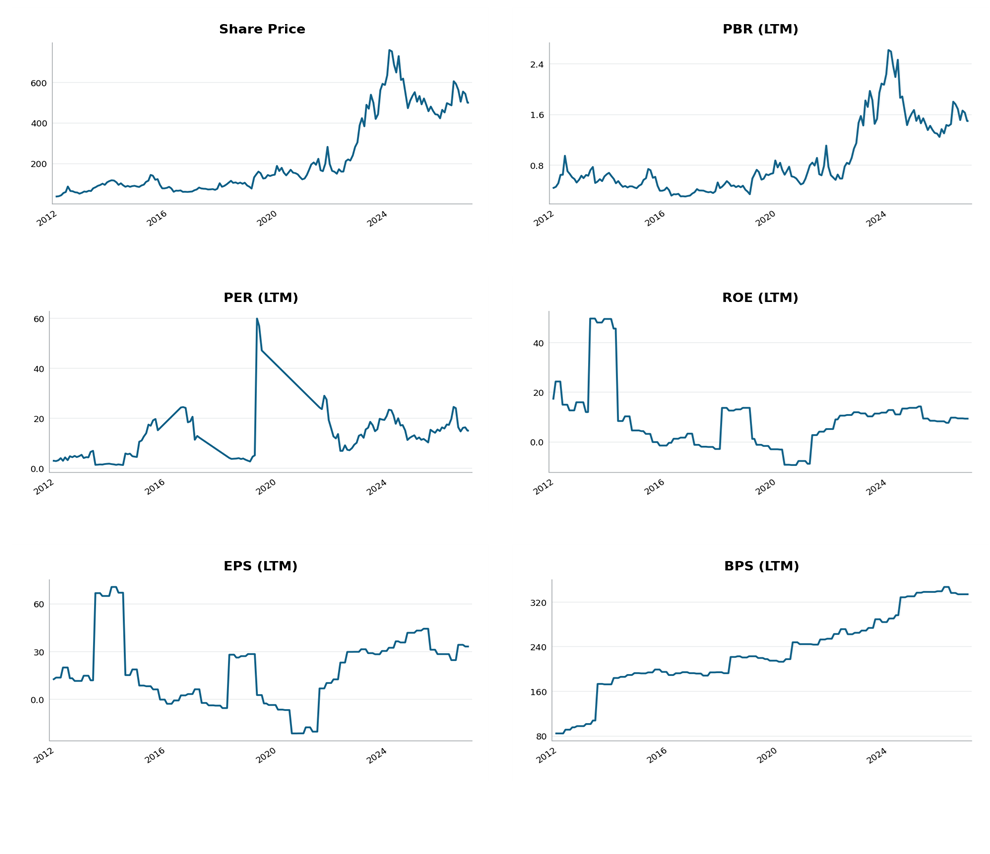
The sharp rise and subsequent fall in the share price show that high barriers to entry do not necessarily translate into increased shareholder value. During the 2022–2023 rally, PBR expanded on expectations driven by crematoria scarcity, higher funeral service unit prices, and earnings growth. In our view, during 2024–2025 the sustainability of earnings and capital efficiency were tested against those heightened expectations, leading to PER and PBR contraction. Current valuations have corrected some of the earlier excess, but an improvement in earnings quality is necessary for a re-rating.
The greatest competitive advantage lies less in pricing power than in the difficulty of replicating capacity and locations. Tokyo Hakuzen’s six facilities and 70% cremation share in the 23 wards constitute a strong competitive base. At the same time, the high throughput of its grate-type furnaces provides an advantage when supply and demand are tight. The long-term rise in deaths associated with population ageing is a tailwind, but deaths by area, cremation volumes and facility utilisation rates fluctuate in the short term. Expansion of public facilities and administrative monitoring of fees also warrant consideration.
High margins should not automatically be regarded as evidence of permanent pricing power. The 34.6% segment operating margin in Funeral Revenue-Generating Activities in FY3/2026 is attractive, but it is affected by funeral hall usage, take-up rates for ancillary services, the trend towards smaller funerals and facility maintenance costs. Cremation has a strong public-interest character, and social opposition to fee revisions or administrative action could cap margins.
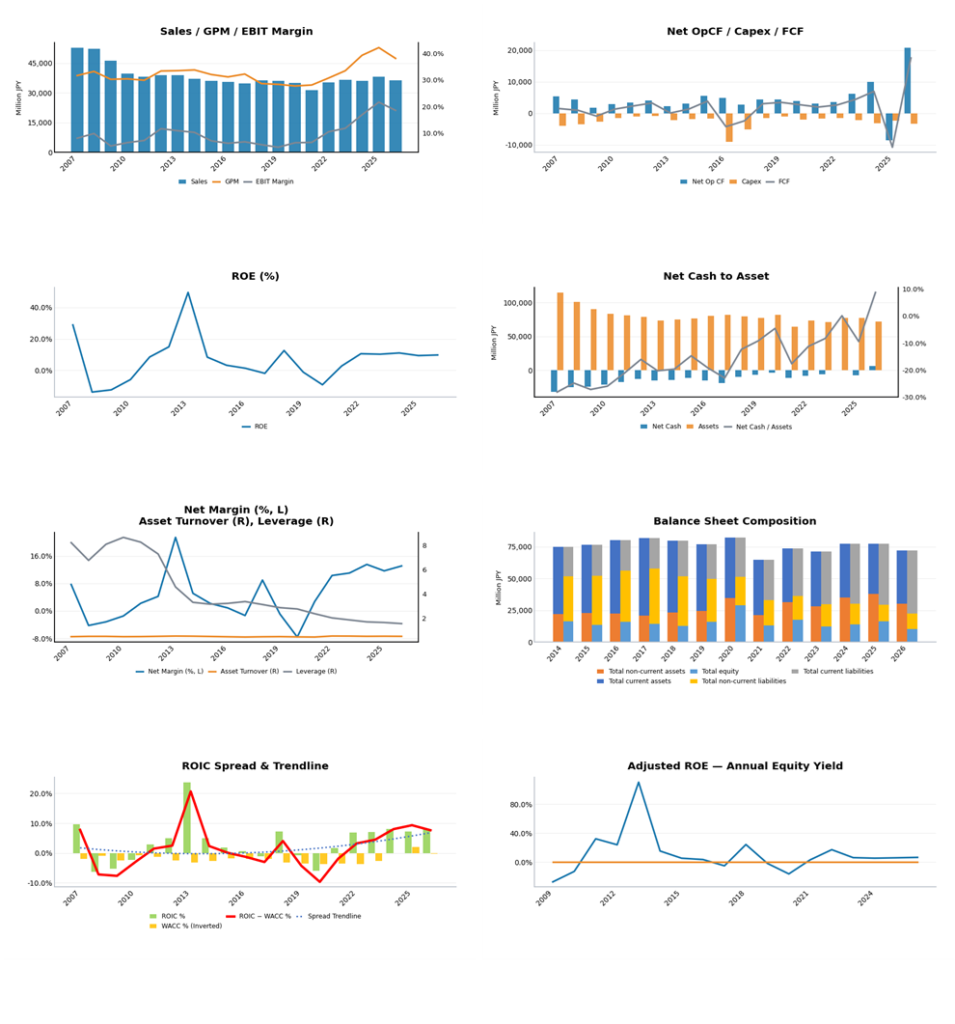
Growth in consolidated revenue alone is not a measure of increased enterprise value. In FY3/2026, revenue was JPY36.228bn, operating profit JPY6.740bn and the operating margin 18.60%. The company’s FY3/2027 plan calls for revenue of JPY39.4bn, operating profit of JPY7.1bn and an operating margin of 18.02%, implying a margin decline despite revenue growth. We distinguish the low profitability of Information, losses in Human Resources, and project dependence in Asset Consulting, and emphasise Funeral’s sustainable profits.
The substantial negative FCF in FY3/2025 was driven primarily by increased operating loans in Asset Consulting, rather than higher capital expenditure. In FY3/2024, operating cash flow was JPY10.021bn and investing cash flow was negative JPY9.038bn, leaving positive FCF of JPY0.983bn. In FY3/2025, by contrast, operating loans increased by JPY15.060bn in connection with a major real-estate-related project, and operating cash flow was negative JPY8.453bn. The project was completed in July 2025, the operating loans were recovered in full, and no losses were incurred. As a result, operating cash flow recovered to JPY20.852bn in FY3/2026. Nevertheless, the funding burden and cash-flow volatility associated with large projects continue to warrant attention.
The commitment to shareholder returns merits recognition, but a track record of capital allocation is needed to increase investment conviction. The forecast annual dividend of JPY13.34 for FY3/2027 represents a 2.89% yield at a share price of JPY462. Given the high proportion of shares held by major shareholders and insiders, expected returns on investment projects, the distribution of surplus cash, execution of share buybacks and accountability are important from a minority shareholder’s perspective. At a forecast ROE of 9.35%, it cannot be concluded that competitive advantages in the existing businesses have translated sufficiently into improved capital efficiency. A confirmed improvement in sustainable FCF and the ROIC spread, in addition to greater shareholder returns, would warrant an upgrade from CAUTIOUS BUY to BUY.
Financials and Valuations | Reassessing margins, cash generation and ROE
Revenue and operating margin. While the Funeral business supports consolidated profit, there is scope to improve profitability in Information and Human Resources. Operating profit fell from JPY8.302bn in FY3/2025 to JPY6.740bn in FY3/2026, and a recovery in the group-wide margin needs to be achieved without relying on one-off earnings.
Operating cash flow, capital expenditure and FCF. As changes in operating loans cause substantial fluctuations in operating cash flow, we separate working-capital movements related to Asset Consulting from operating cash flow and assess underlying FCF after maintenance and replacement investment.
ROE, ROIC and asset efficiency. Forecast ROE is 9.35% (forecast EPS of JPY31.2 divided by the latest BPS of JPY333.61). Historical peaks in ROE do not guarantee sustained high profitability. We focus on how asset turnover and financial leverage interact with improvements in the net profit margin, and whether the ROIC spread remains consistently positive.
Share price, PER and PBR. During the share-price rally, PBR expanded ahead of earnings growth, while valuation multiples contracted during the correction. A forecast PER of 14.81x and PBR of 1.38x are levels at which the shares merit consideration given the advantages of the cremation business but cannot be deemed significantly undervalued relative to forecast ROE of 9.35%. To gain the conviction required for a conventional BUY, we would want to see greater earnings stability and higher capital efficiency.
Source: FactSet | Data as of 05 Nov 2026